
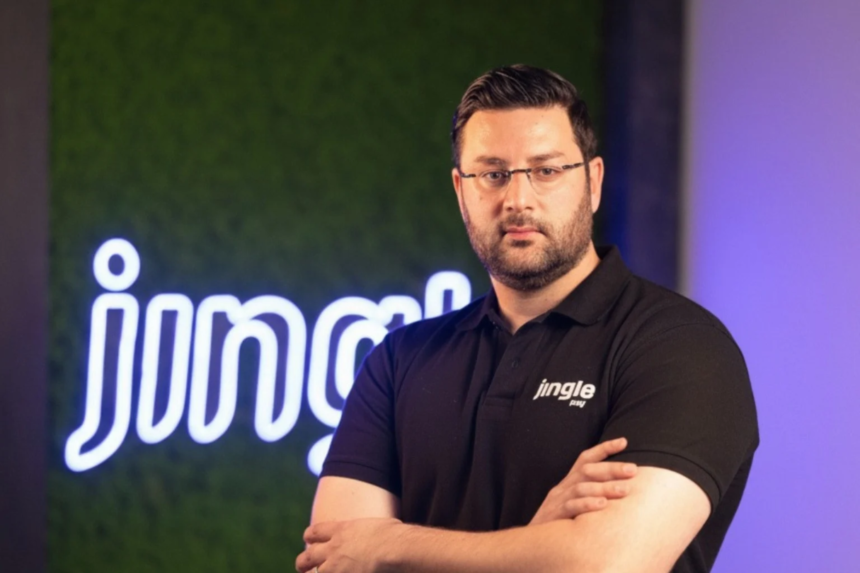
Amir Fardghassemi is steering Jingle Pay’s expansion in the digital payments sector, with a focus on scaling its services and making international money transfers easier.
Amir Fardghassemi, founder and CEO of Jingle Pay, is building a global money movement platform designed to make cross-border payments faster, more accessible, and easier to manage.
With more than 15 years of experience in finance, including running a hedge fund and building and selling companies, Fardghassemi set out to address a problem that continues to affect international payments: sending money across borders can still be slow, expensive, and complicated.
Jingle Pay began as a consumer app serving expatriates in the UAE who wanted to send money home. Its original model was built around a remittance marketplace that allowed users to compare providers’ exchange rates and choose the most competitive option.
Since then, the company says it has processed more than $4.5 billion in transfers across over 150 countries and more than 99 currencies, saving customers over $67 million.
The experience of operating that marketplace led to a broader business opportunity. To compare providers and route transfers efficiently, Jingle Pay had to connect with multiple payment networks, manage liquidity, screen transactions, and handle settlement.
Those capabilities eventually became the foundation of its infrastructure business, which now serves financial institutions and other companies.
From Remittance App to Money Movement Infrastructure
Jingle Pay continues to operate its consumer app in the UAE, Pakistan, and Bahrain, with Canada planned as its next market. Its underlying infrastructure supports more than 20 payment corridors across Asia-Pacific, the Middle East and North Africa, and Latin America.
The platform is designed to connect financial institutions, money transfer operators, and digital wallets to multiple currencies and payout methods through a single integration.
A partner can use the system to send money to a bank account, a digital wallet, or a cash-pickup location. Jingle Pay manages the payment route, liquidity, screening, and settlement behind the scenes.
The company also uses AI to support tasks such as transaction screening, corridor pricing, liquidity forecasting, and identifying potentially suspicious transactions.
Fardghassemi describes the platform as an AI-first operating system for global money movement.
“Information went global twenty years ago. Money never did,” he says. “We are not building a faster version of that chain. We are replacing it with one system.”
Pakistan Provides a Foundation for Global Expansion
Pakistan has been an important market in Jingle Pay’s development. The company says it became a leading player in transfers into the country, giving it experience in managing the operational challenges of cross-border payments at scale.
These include liquidity management, settlement, regulatory compliance, local banking requirements, and the different payment networks used to deliver funds.
Jingle Pay has used that experience to develop infrastructure that can be adapted to additional markets without rebuilding the entire system for every new corridor.
Each market has its own requirements. A payment route into the Philippines, for example, differs from one into India. The company’s approach is to use a common platform while configuring the local requirements of each corridor.
This model underpins its expansion across multiple regions and allows partners to access additional destinations through the same infrastructure.
Connecting Traditional Payments With Stablecoins
Jingle Pay is also working to connect conventional financial systems with stablecoins and digital wallets.
The platform is designed to allow partners to send traditional currencies and deliver funds through different payment methods, including bank accounts, wallets, and cash-pickup services. It can also use stablecoins as a settlement rail where permitted and supported.
For example, a payment could begin in dollars and reach a recipient as pesos in a wallet, or use a stablecoin to fund a transfer before delivering rupees to a bank account.
The goal is to make the underlying payment method largely invisible to the sender and recipient.
Fardghassemi views stablecoins as an additional payment rail rather than a replacement for the banking system. He argues that the value lies in connecting traditional finance and digital assets within a common framework.
Partnerships and Regulatory Approvals
Jingle Pay’s partnerships reflect its shift towards infrastructure and business-to-business payments. MoneyGram made a strategic investment in the company in 2022, while Mastercard partnered with the platform to introduce physical and virtual cards.
The company also says Western Union and BOTIM, the UAE’s messaging app, use its infrastructure for payment flows.
Regulation is another important part of its operating model. According to the company, Jingle Pay is regulated by the Dubai Financial Services Authority, with permissions covering money transmission, payment instruments, stored value and the arrangement of money services.
It also holds a licence in Canada and regulatory approvals in Bahrain and Pakistan, where its consumer app operates alongside its UAE business. The company says it has obtained virtual-asset permissions to support connections between traditional currencies and digital assets within a regulated framework.
These approvals are central to its expansion strategy, as cross-border payments require compliance with the rules of the markets and financial systems involved.
Jingle Pay Targets $10 Billion in Annual Payment Volume
Jingle Pay says it is processing approximately $5 billion in annual payment volume from its base in Dubai. Fardghassemi’s next target is to reach $10 billion.
The company is pursuing that goal through a treasury-as-a-service product that has recently gone live, alongside the expansion of consumer and business payments across its growing network of corridors.
Its strategy is to add new markets and payment endpoints without having to build a separate operating system for each one.
“Five billion is a receipt, not a trophy,” Fardghassemi says.
For him, the longer-term objective is to let money enter the platform in one currency or format and arrive anywhere else as cash, a wallet balance, or a bank credit, without users needing to understand the infrastructure behind the transaction.
Jingle Pay’s evolution from a remittance app into a payments infrastructure provider reflects that ambition. Its next phase will depend on expanding its network, supporting more financial institutions, and connecting traditional payment systems with newer digital rails.